When the unthinkable happens and fire ravages your home or business, the immediate aftermath can feel incredibly overwhelming. Amidst the shock and the clean-up, one crucial task often emerges: documenting your losses for insurance purposes. This is precisely where a fire loss inventory list template becomes an invaluable tool, transforming a daunting process into a manageable, step-by-step approach that ensures you account for every item damaged or destroyed. It acts as your guide, helping you systematically record everything needed to support your claim and move towards recovery.
Without a comprehensive inventory, recalling every possession lost in the chaos of a fire is nearly impossible. Memories can be unreliable under stress, and the sheer volume of items, from major appliances to the smallest kitchen utensil, makes a mental inventory impractical. Insurance companies require detailed proof of loss, and a well-prepared inventory can significantly streamline the claims process, helping you avoid disputes and ensuring you receive a fair settlement that accurately reflects your losses.
Preparing such a list might seem like another burden during a trying time, but it is an investment in your future stability. This article will walk you through the essential components of a robust fire loss inventory, discuss best practices for compiling your list, and explain why having a structured approach is the most effective way to navigate the complexities of an insurance claim after a fire.
Rebuilding Your Life After Fire: Why a Detailed Inventory Matters
The emotional toll of a fire can be immense. Beyond the immediate danger, witnessing the destruction of cherished belongings and the disruption to your daily life is a profoundly distressing experience. In the wake of such a disaster, focusing on administrative tasks like insurance claims can feel like an insurmountable hurdle, especially when your mind is preoccupied with safety, temporary housing, and emotional recovery.
However, despite the emotional distress, prompt and accurate documentation is critical. Insurance policies are contracts that require policyholders to demonstrate the extent of their losses. Without a clear, itemized list of what was damaged or lost, your claim could be delayed, undervalued, or even denied. This is where a meticulously prepared inventory acts as your most powerful advocate, providing concrete evidence of your possessions before the fire.
Imagine trying to remember every piece of clothing, every book, every tool, or every decorative item you owned across an entire household. The task is formidable, to say the least. A structured inventory helps you systematically work through each room and each category of item, ensuring that nothing important is overlooked. It brings order to the chaos and provides a tangible record when your memories might be hazy or incomplete.
What to Include in Your Inventory
When compiling your fire loss inventory, the goal is to be as comprehensive as possible. Start by categorizing items. Think about furniture in each room: sofas, chairs, tables, beds, mattresses, dressers, bookshelves. Then move to appliances, both major (refrigerators, stoves, washers, dryers) and small (toasters, blenders, coffee makers, microwaves). Don’t forget electronics like televisions, computers, tablets, gaming consoles, and all their associated accessories.
Beyond the obvious large items, delve into the details. Clothing, shoes, and accessories for every member of the household represent significant value. Kitchenware includes dishes, pots, pans, cutlery, glassware, and storage containers. Linens such as bedding, towels, and curtains also need to be accounted for. Think about collectibles, artwork, jewelry, musical instruments, and any unique or high-value items that might require special appraisal. Tools in a garage or shed, sporting equipment, children’s toys, books, and even pantry staples contribute to the overall loss.
Crucially, documentation plays a vital role. If you have any pre-fire photographs or videos of your home, these can be incredibly useful to supplement your written list. Keep receipts for major purchases if possible. Even if physical receipts are lost, credit card statements or online purchase histories can help establish proof of ownership and value. For items without receipts, estimating the age and condition, along with the approximate purchase price, becomes necessary.
Understanding the difference between replacement cost value (RCV) and actual cash value (ACV) is also important. RCV covers the cost to replace the item with a brand new one, while ACV accounts for depreciation based on the item’s age and condition. Your insurance policy will specify which method applies, but compiling an inventory that includes estimated values for both can put you in a stronger negotiating position.
Crafting Your Inventory: Practical Steps and Essential Tips
Beginning the inventory process can feel like a daunting undertaking, particularly when you are still reeling from the shock of the fire. However, approaching it systematically and breaking it down into manageable steps can make it less intimidating. The most effective way to start is to secure a dedicated fire loss inventory list template, which provides a ready-made structure for your documentation.
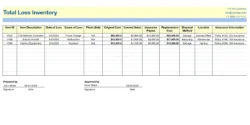
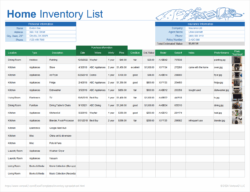
A well-designed template often includes columns for item description, room location, quantity, date of purchase, original cost, estimated replacement cost, and notes for any supporting documentation like photos or receipts. This organized format helps ensure consistency and thoroughness. Even if you don’t have access to your property due to safety concerns, you can start by listing items you vividly recall from each room, using the template as a mental framework to jog your memory.
When you are able to access the property, or even when recalling from memory, tackle the inventory room by room. This methodical approach minimizes the chances of missing items. Start with a room you remember well and work your way through. For each item, be as descriptive as possible. Instead of just writing “chair,” specify “living room armchair, green velvet, purchased 2018.” The more detail you provide, the clearer the picture will be for the insurance adjuster.
Consider these practical tips as you fill out your inventory:
- Detail everything room by room, including contents of closets and drawers.
- Gather all possible documentation such as photos, videos, receipts, and even user manuals.
- Estimate values realistically; research current market prices for similar items if original costs are unknown.
- Don’t forget the small things like toiletries, spices, cleaning supplies, and decorative accents; their cumulative value adds up significantly.
- Be patient and thorough, as this process takes time and attention to detail.
This meticulous effort in documenting your losses not only strengthens your insurance claim but also provides a sense of control during a chaotic period. It prepares you for discussions with your insurance adjuster, allowing you to confidently present your case and advocate for a fair and comprehensive settlement.
Navigating the aftermath of a fire is undeniably one of life’s most challenging experiences. While the emotional and physical recovery takes precedence, the practical step of creating a detailed inventory is fundamental to rebuilding your life. It serves as the bedrock of your insurance claim, providing clarity and substance in a time of confusion, and ultimately helping you reclaim what was lost.
Taking the time to compile a comprehensive list of all your damaged or destroyed possessions ensures that you receive the maximum possible settlement from your insurance provider. This proactive approach, though demanding, empowers you to move forward with the necessary resources to repair, replace, and restore your home and your peace of mind.